Back to school – for £70,000 a year?
Being able to pay school fees and being able to afford school fees can be two very different things.
By Robert Wilcocks, Chartered MCSI
Founder, Quantum Life · Chartered Member of the CISI · Registered Life Planner®
2 min read · Published · Updated
I read recently that fees at one of Britain’s leading boarding schools are now nudging £70,000 a year. For some overseas pupils, they’ve sailed past it.
£70,000. Per child. Per year. Before you’ve bought a single blazer, hockey stick or inexplicably expensive school ski trip.
A client told me last year she’d stopped opening the fee invoices. She just paid them. Looking felt worse than not looking.
I understand that. But it’s not a plan.
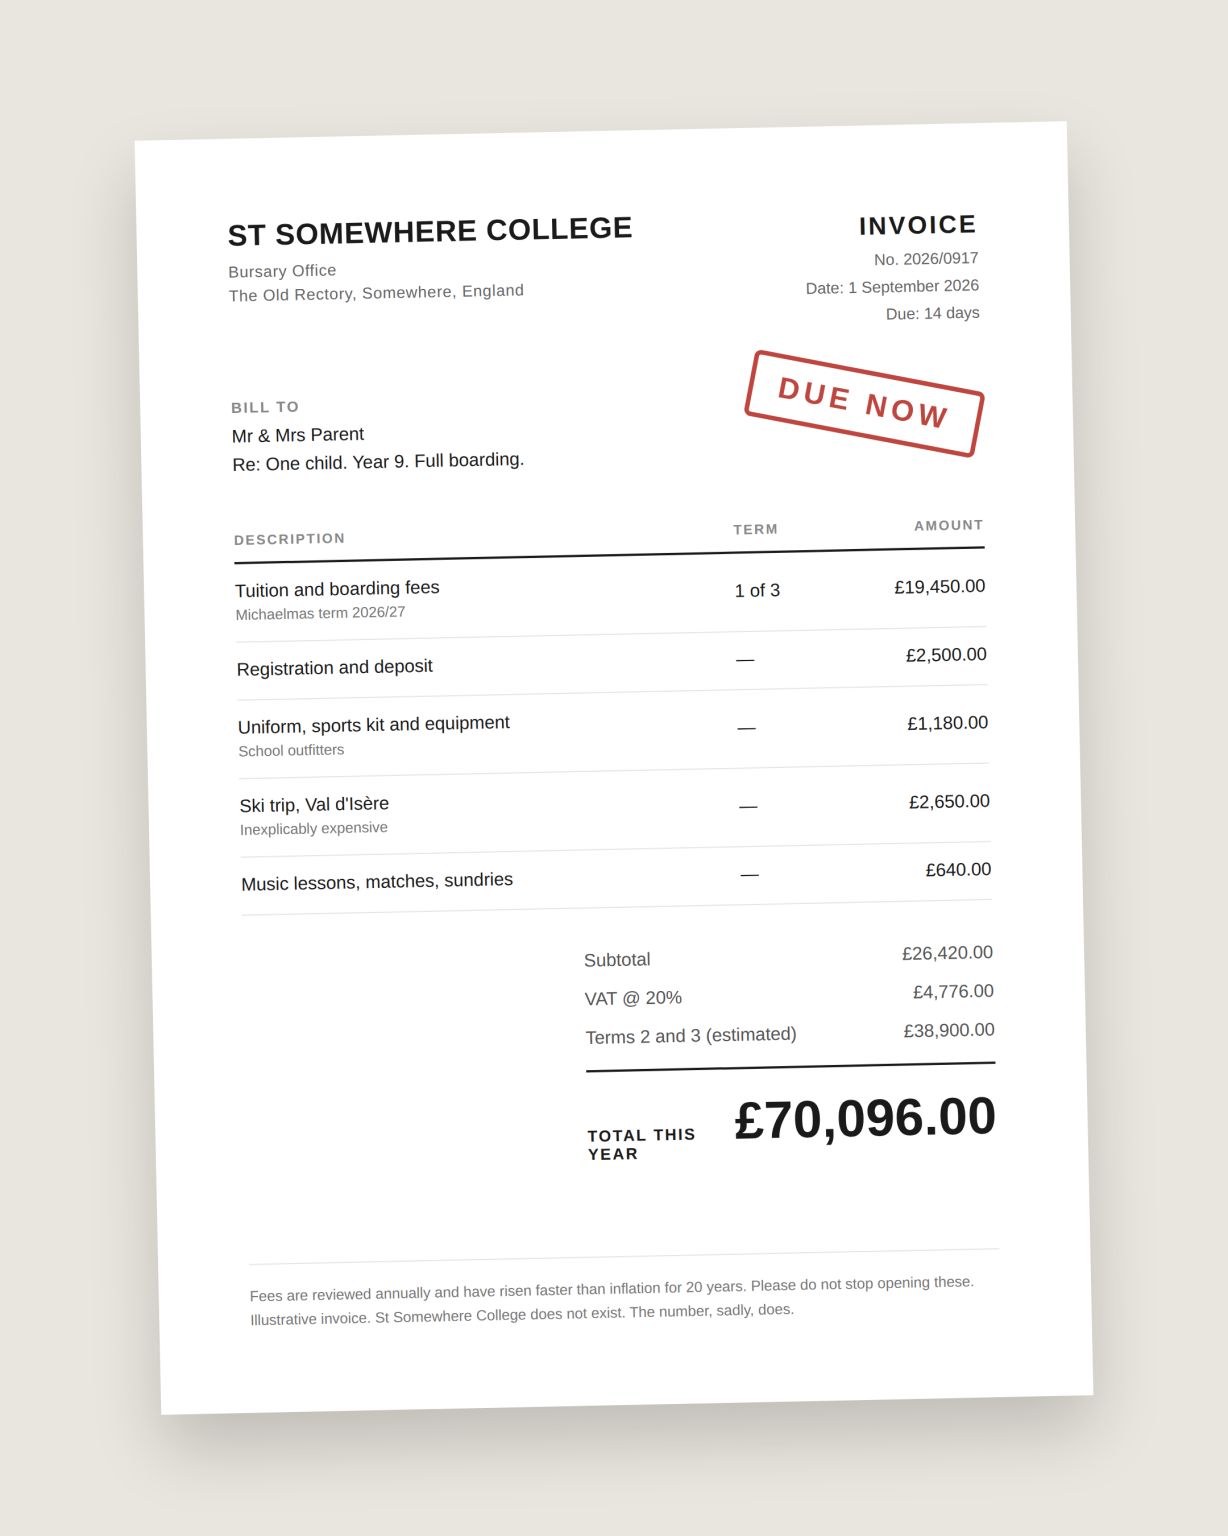
School fees have risen faster than inflation for 20 years. Then in January 2025 the Government added VAT at 20%.
The Independent Schools Council found average fees jumped 22.6% in a single year. Not every school passed on the full amount. But the maths has changed for every family paying them.
With two or three children, from nursery to sixth form, this can become one of the biggest financial commitments your family ever makes. It’s often the same with one.
So here’s what I’d do if you sat across from me.
First, the uncomfortable bit. We add up the total cost over the remaining years, with fees rising as they do. It’s usually a bigger number than people expect. But it’s better to know now than to find out halfway through.
Then we work out where the money is actually coming from. Salary? Bonuses? Investments? Your business? Grandparents?
And is there a smarter way to pay? Could grandparents help, and would that also cut their inheritance tax bill?
Finally, we ask what has to give. Can you still retire when you want to? Take the holidays you enjoy? Help the children with their first homes? Or are you spending so much educating them that there won’t be much left to help them afterwards?
Being able to pay school fees and being able to afford school fees can be two very different things.
There’s no single right answer. For some families, private education is one of the best things they could spend their money on. Great. That’s what money is for. Just make it a conscious choice, not a direct debit you’ve stopped looking at.
At Quantum Life, we work backwards from the life you want your money to make possible and model all of it together. School. Retirement. Property. Travel. Helping the children. The lot.
Because being able to pay school fees and being able to afford school fees can be two very different things.
Rob
Frequently asked questions
How much have UK private school fees risen?
School fees have risen faster than inflation for 20 years. After VAT at 20% was added in January 2025, the Independent Schools Council found average fees jumped 22.6% in a single year, although not every school passed on the full amount.
How should I plan for school fees?
Add up the total cost over the remaining years with fees rising, work out where the money will come from, consider whether there is a smarter way to pay, and check what has to give, such as when you retire or how much you can help the children later.
Can grandparents help pay school fees?
Yes, grandparents can help, and depending on how it is done this may also reduce their Inheritance Tax bill. The right approach depends on their circumstances, so it should be planned rather than improvised.
Robert Wilcocks, Chartered MCSI
Founder, Quantum Life · Chartered Member of the CISI · Registered Life Planner®
About Robert →